

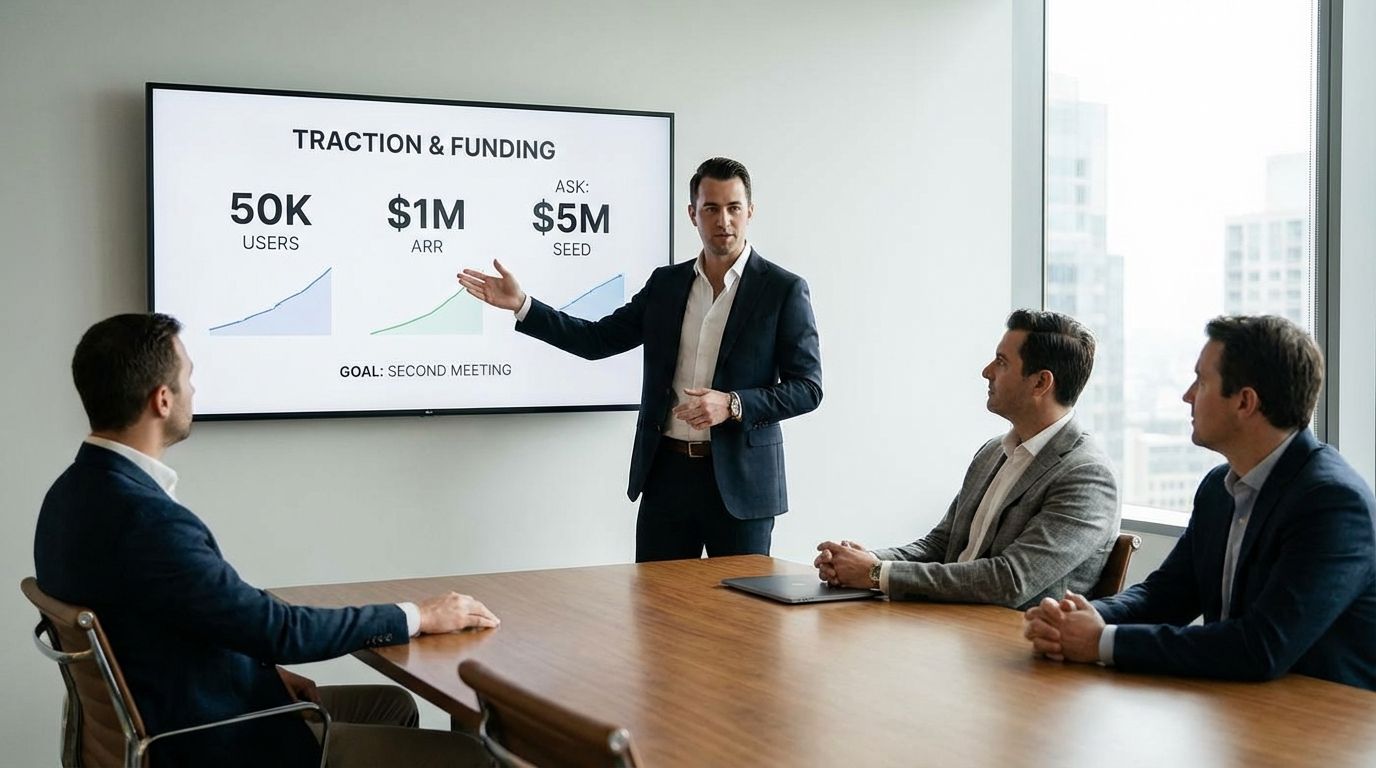
You secure funding by making it easy for an investor to understand, remember, and repeat your story, then proving you can execute with measurable traction and a clean plan for what their money unlocks. Your pitch is not a performance, it’s a decision tool that earns the next meeting, triggers diligence, and survives internal forwarding.
This guide shows you how investors scan decks, what they expect you to answer fast, how to build a deck that holds up when you’re not in the room, and how to run the meeting so you control the pace. You’ll walk away with a practical pitch structure, slide-by-slide standards, a meeting plan, and a term-sheet readiness checklist that reduces avoidable mistakes.
How Do You Structure A Pitch So Investors Say “Let’s Take A Second Meeting”?
Your job in the first meeting is to earn a second meeting with momentum, not to “close” the round on the spot. Investors use early meetings to pattern-match: does the business click quickly, does the founder communicate with precision, and is there proof that demand exists or can exist soon.
Run your narrative in a straight line that is easy to retell. Start with a one-sentence description that includes the buyer, the painful problem, and the result you deliver. Then move through problem, solution, traction, go-to-market, market size, team, and the ask, in that order, with minimal detours.
Keep the “why now” present in your language without turning it into a lecture. Explain what has changed that makes this possible now, then show the wedge that gets you in the door. Investors lean toward businesses that can start narrow, win fast, then expand.
Make your pitch legible at speed. Many investors skim decks quickly, then decide whether to spend more time. Your first three slides must make the business understandable without narration, and your later slides must convert curiosity into confidence.
Use this proven backbone and then tailor it to stage:
- One-liner: what you do, who pays, and the measurable outcome.
- Problem: specific, frequent, expensive, owned by a clear buyer.
- Solution: what you built, how it works at a high level, what is different.
- Traction: revenue, retention, pipeline, usage growth, pilots, repeatable signals.
- Go-to-market: channel, sales motion, sales cycle, CAC experiments, conversion.
- Market: initial beachhead, expansion path, why it can become big.
- Competition: alternatives, why you win, why you keep winning.
- Team: why you are the right operators for this exact problem.
- Ask: amount, instrument, milestones, timeline, use of funds.
When you deliver this structure, you create a clean “investor memo” in their head. That is what gets forwarded to partners, associates, and co-investors without distortion.
How Many Slides Should Your Pitch Deck Be, And What Do Investors Actually Read?
Investors do not “read” your deck the way founders expect. Many skim, jump around, and spend minutes, not hours. DocSend’s pitch-deck metrics have shown average time on deck around the low-minutes range, with a commonly cited figure of 2 minutes, 24 seconds on their pitch deck metrics page, which is a blunt reminder that your deck must land fast. A separate DocSend analysis of decks in 2019 reported an average of 3 minutes, 44 seconds, reinforcing that investor attention is limited even when it is higher than today’s benchmarks.
Design for skim speed. Your slides must communicate one idea each, with a headline that states the claim and the content that proves it. Dense paragraphs kill comprehension. Small fonts signal that you are hiding weak thinking behind volume.
Keep your core deck lean enough to forward. A useful target for many seed and pre-seed decks is roughly 10 to 15 slides, with an appendix that holds deeper detail. That gives you enough space to answer the core questions without forcing an investor to hunt for meaning.
Build for two use cases: a “send-ahead” deck that stands alone, and a “live” flow that you can present in a meeting. The send-ahead deck must be readable without you. The live flow must keep the meeting moving and prevent slide-by-slide narration.
Assume your deck will get forwarded internally. Partners often see a deck after someone else has already skimmed it. If your message depends on your voice, your meeting becomes the only way to understand the business, and that slows the investor’s internal process.
What Are The Must-Have Slides Investors Expect In A Seed Or Pre-Seed Deck?
Investors expect you to answer the same set of questions in almost every early-stage raise. The exact template matters less than clarity. You can rename slides, you can reorder for your motion, you can compress, but you cannot skip the fundamentals and expect a clean process.
Use a “minimum viable” set of slides that mirrors how investors make decisions. A commonly discussed set includes problem, solution, market, traction, business model, go-to-market, and team with the ask. That list shows up often in investor-facing guidance and mainstream summaries of YC-style expectations, while YC’s own design advice emphasizes tight communication and removing clutter over strict templates.
Here is a slide list that works for most founders raising pre-seed or seed:
- Cover: company name, one-liner, contact.
- Problem: a real pain, with a buyer who owns the budget.
- Solution: what you built, how it solves the pain, why it is defensible.
- Product: screenshots, workflow, demo link, “how it works” at a high level.
- Traction: proof that demand exists, with growth and retention where possible.
- Business Model: pricing, margin logic, what scales, what doesn’t.
- Go-to-Market: channel, motion, conversion points, sales cycle, learnings.
- Market: beachhead, expansion path, why it can become large.
- Competition: alternatives, why you win today, why you win later.
- Team: why you can execute, what you have shipped, domain advantages.
- Ask: amount, milestones, runway, what changes after the raise.
Keep the “ask” operational. Investors are not buying your optimism, they are buying a credible plan that turns capital into de-risking milestones. State the raise size, the instrument you’re using, and the execution milestones you will hit with that funding.
Should You Send The Pitch Deck Before The Meeting Or Present It Live?
Sending your deck ahead usually improves the meeting. It lets the investor skim on their own schedule, then use the live time for depth, risks, and decision-making. It also reduces the chance that the meeting gets consumed by basic comprehension questions that a well-built deck can answer.
Control what you send. Use a forward-safe version that does not include sensitive operational details you would regret sharing widely. Then keep a deeper appendix or a follow-up packet ready for serious interest.
Use a simple operating rule that works across angels and funds: send the deck 24 to 48 hours before the meeting, confirm they received it, then open the meeting with a tight verbal pitch and a plan for how the time will run. If they did not read it, the meeting still succeeds because your verbal pitch and your slides can stand alone.
Run two deck modes without overcomplicating it:
- Teaser deck: concise, safe to forward, enough to trigger a follow-up.
- Live deck: the same spine, with prompts for demo, timing, and Q&A.
Use secure sharing when you send materials. Track views and time spent so you know whether to open with the full story or jump straight to risks and diligence. Treat that data as a signal for meeting control, not as ego validation.
What Traction Do You Need To Raise If You Don’t Have Revenue Yet?
If revenue is not present, sell proof of pull. Investors still need evidence that a real buyer wants this and will keep wanting it. The goal is to show that the business is moving from an idea to a repeatable system.
Use traction that matches your business model and stage. For product-led motions, focus on activation, retention, and weekly usage. For sales-led motions, focus on pipeline quality, cycle time, conversion points, and early expansion signs. For enterprise pilots, show paid pilots when possible, strong LOIs with credible buyers, and a clear timeline from pilot to contract.
Investors punish traction without meaning. A big number with no denominator, no growth rate, and no retention creates more questions than confidence. You want to make it easy to see the slope, the repeatability, and the reason it should continue.
Present traction in three layers:
- Input metrics: leads per week, outbound reply rate, cost tests, demo set rate.
- Activation metrics: time-to-value, setup completion rate, first “aha” action.
- Behavior metrics: retention, usage frequency, expansion, referrals.
Then connect those metrics to a near-term milestone plan. Investors fund progress. You need two or three milestones that turn the business into a clearer bet: conversion from pilot to contract, retention above a threshold, repeatable acquisition channel, or a pricing model that proves willingness to pay.
What Terms Matter Most In A Funding Offer, And What’s “Standard” Now?
Headline valuation is not the only term that shapes founder outcomes. Pay attention to terms that control downside, control, and future fundraising. A clean term sheet keeps your cap table fundable and reduces surprises later.
Learn the few terms that matter most and insist on plain-English explanations. Focus on liquidation preference, participation, pro-rata rights, option pool treatment, protective provisions, board or control rights, pay-to-play, and any unusual redemption or penalty mechanics. If a term cannot be explained in simple language, treat it as a risk until proven otherwise.
When assessing “standard,” anchor on mainstream templates and market data, not anecdotes. The NVCA model legal documents are a widely used baseline in U.S. venture deals, and the NVCA has released updates that keep those documents current for common financing scenarios. Treat those model docs as a translation layer when comparing term sheets from different investors.
Market conditions shift what investors request. Deal-term reporting from platforms that track financings shows that structures and preferences can move with the market. That does not mean you accept every investor-friendly term. It means you need a clear range of acceptable outcomes and a lawyer who can flag what is normal, what is negotiable, and what will scare future investors.
Run a simple discipline before signing anything: model your outcomes at multiple exit values. If a term sheet looks fine at a big exit but punishes you at modest outcomes, it can change how you make decisions as a company. Optimize for clean terms and future fundability, not just headline price.
What Should Be In A Startup Pitch Deck?
- One-liner
- Problem
- Solution
- Product
- Traction
- Go-to-market
- Business model
- Market
- Competition
- Team
- Ask
- Milestones
Walk Out With A Pitch That Gets Follow-Ups
A fundable pitch makes your company easy to grasp quickly, then backs the story with proof and a plan that investors can underwrite. Keep the deck tight, make the first slides do the heavy lifting, and build every slide so it works when forwarded. Send the deck ahead in a forward-safe format, then use the meeting to handle risks, metrics, and decision criteria. Treat traction as evidence with clear denominators and slopes, then tie the raise to two or three execution milestones. When term sheets arrive, focus on the terms that shape outcomes and future rounds, and anchor your comparisons to established model documents and market reality.
References
- Practical Design: Pitching | Y Combinator
- How to Design a Better Pitch Deck | Y Combinator
- DocSend Startup Index – 2021 Pitch Deck Metrics | DocSend
- How startup fundraising is different in 2019 | DocSend
- NVCA Releases 2025 Updates to Model Legal Documents | NVCA
- Got an investor meeting (Angel) in couple days where I’ll present the pitch. Should I send the pitch deck to them before hand? | r/ycombinator
- What to include in the pitch deck? | r/startups
- I’ve seen hundreds of pitch decks this year and here is my learnings | r/Entrepreneur
- 7 Must-Have Slides In Your Pitch Deck (According To Y-Combinator) | Forbes
- Structure remains persistent in VC rounds in ‘24 | Carta

